
Many artificial intelligence hardware and cloud companies rely on massive multiyear contracts with top software developers to sustain their rapid growth.
But financial disclosures from OpenAI are challenging that expectation and sparking sudden selloffs across the technology sector.
A recent report revealed OpenAI achieved about $50 billion in annualized revenue by late September, falling significantly short of the $68 billion to $70 billion projected by the company weeks earlier.
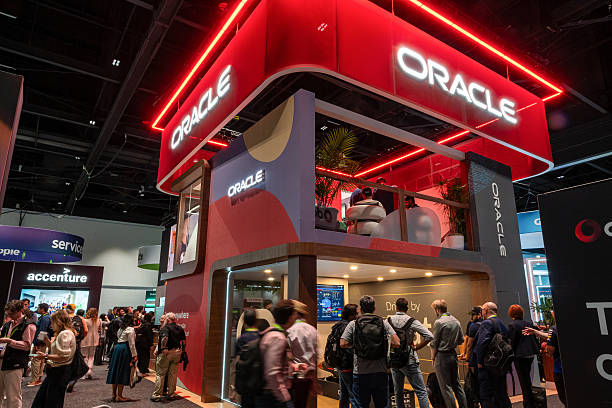
The unexpected figures caused Oracle stock to drop 5.48%, Cloud operator CoreWeave falling to 7.77%, and Nvidia slipping 2.94%.
What Caused the Market Reaction
Annualized revenue is a financial metric that estimates a full year of earnings based on current monthly performance.
And while $50 billion represents a massive number, the technology market trades on future expectations rather than current performance. This immediately created a $20 billion gap between what Wall Street expected and what OpenAI actually delivered, inasmuch as the discrepancy is largely a reflection of the differences in how OpenAI’s partner revenue is counted.
Still, it raises important questions on the direction of funding and generating revenue in the AI industry.
In September 2025, OpenAI had signed an agreement to purchase $300 billion in computing power from Oracle over roughly five years.
With OpenAI now generating lower revenue than forecasted, investors are questioning whether software companies can keep paying for these massive computing commitments.
Why the Revenue Gap Matters
For hardware suppliers and cloud providers, client revenue is the hook. It offers the financial guarantee that developers can afford to rent space in expensive data centers.
The financial strain of building these data centers is already visible at Oracle, as free cash flow dropped into negative $23.7 billion in fiscal 2026 due to heavy capital spending on AI infrastructure.
Yields on Oracle corporate bonds also climbed to 8.1%, pointing to higher borrowing costs and growing financial risk for the enterprise.
For example, technology analyst Dan Ives responded to this risk by removing Oracle from his widely followed list of top winning stocks. This happened right before an exchange traded fund rebalance, which prompted momentum investors to sell their positions.
However, these stock movements reflect near term sentiment and do not establish that Oracle or Nvidia will lose their dominant market positions.
What This Means for the AI Infrastructure Market
The OpenAI shortfall is entering a market where investors are increasingly anxious about data center expansion and AI capital expenditure budgets.
Market observers point out that when actual client earnings fail to meet aggressive forecasts, Wall Street naturally reassesses the speed of infrastructure deployment. The primary fear here is that OpenAI may reduce its compute spending to match its lower revenue trajectory.
As such, if hardware purchases slow down, cloud providers could see their revenue backlogs shrink significantly. Plus, Oracle is entering October, which is historically a weaker seasonal period for its share price.
For now, the stock drop aims to force a necessary financial reality check across the AI industry.
And its wider impact will depend on upcoming corporate earnings reports, customer demand metrics, and how easily cloud providers can manage their heavy infrastructure debts.
